Poland's battery market outlook: what to know in 2026
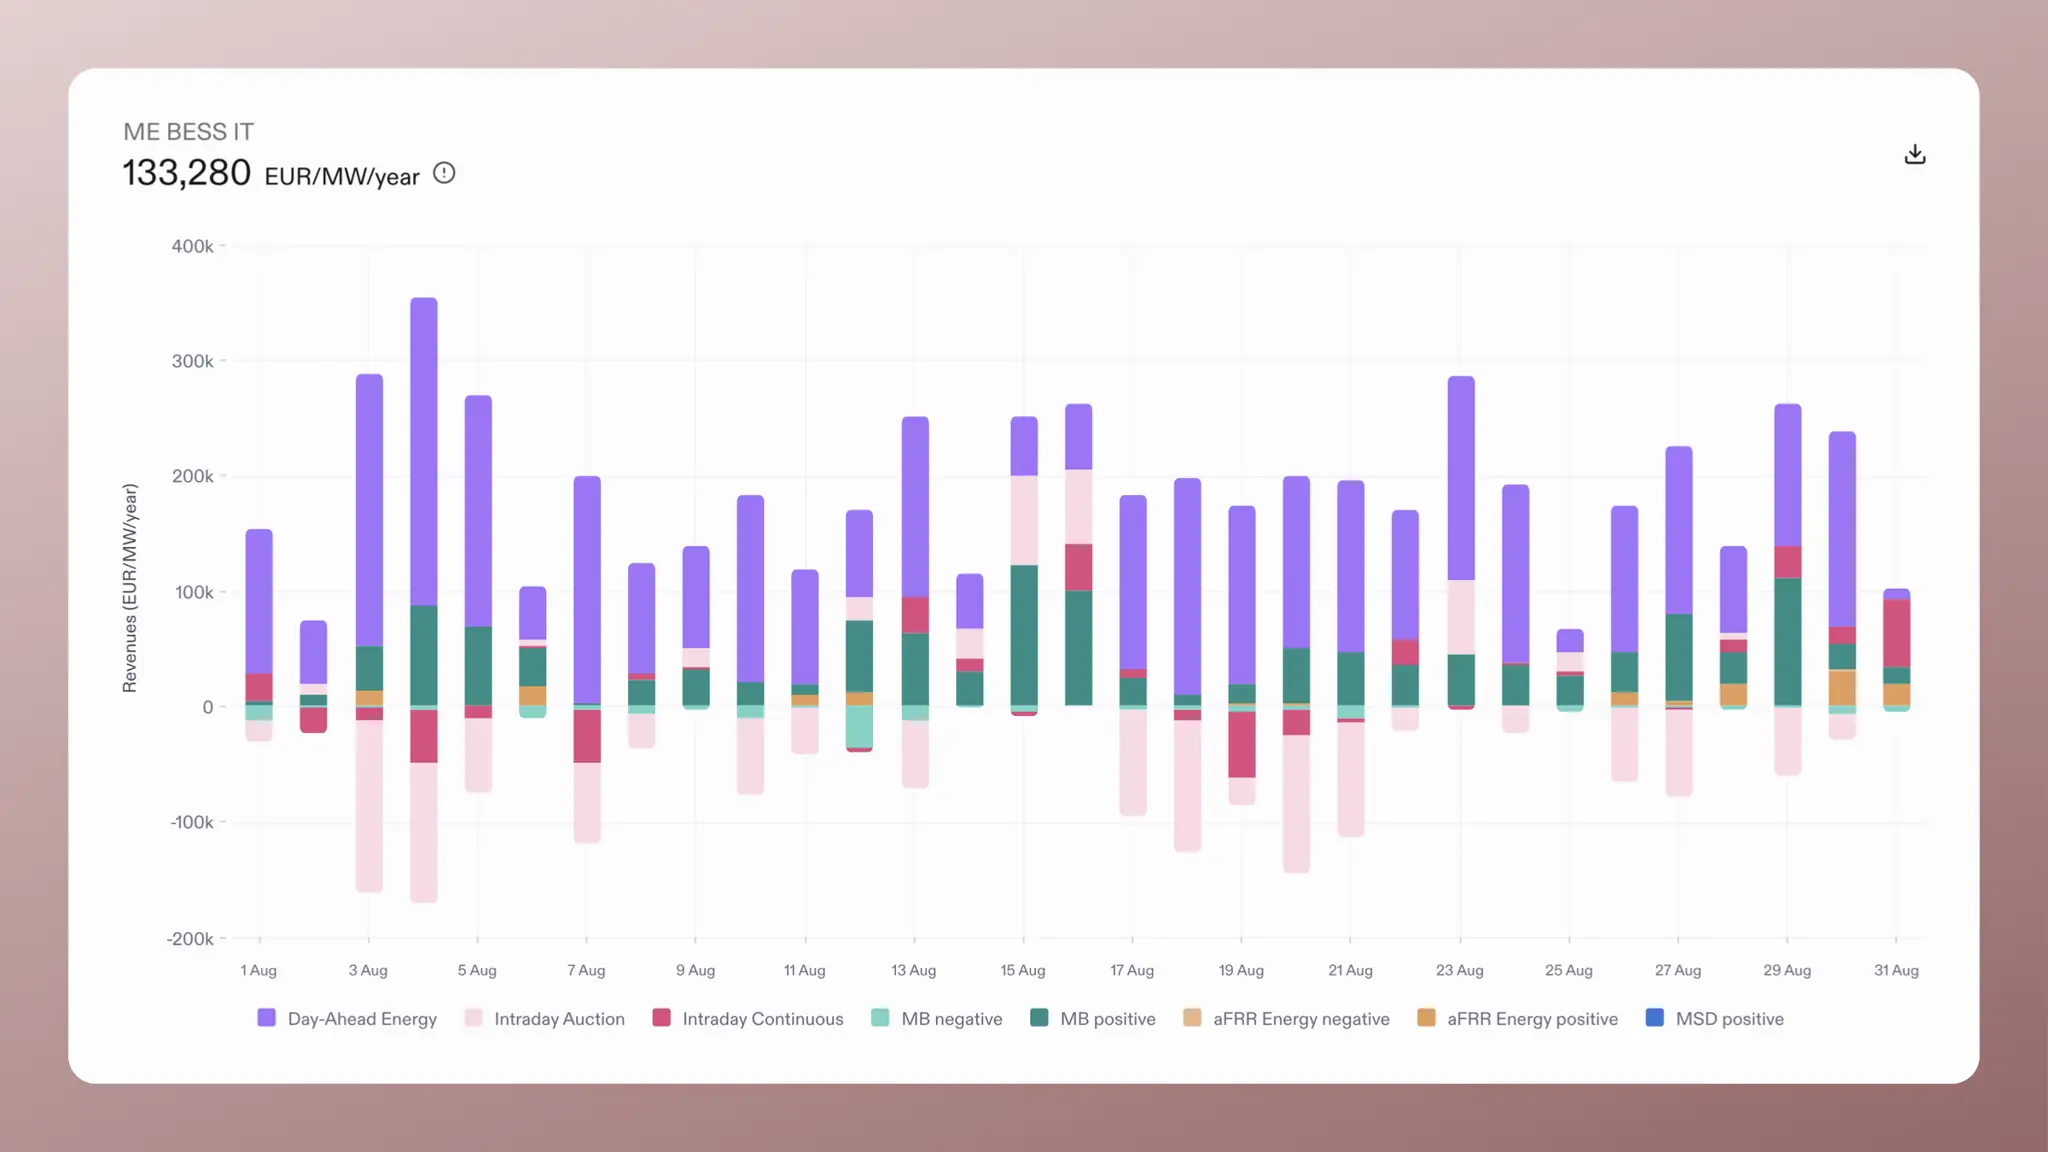
Poland led Modo Energy’s European battery benchmarks in the year to September 2026. Our two-hour Polish battery earned €442k/MW/yr, more than twice as much as the equivalent battery in Germany.
Most of that revenue came from providing reserves to PSE, Poland’s grid operator. PSE buys just 1.8 GW of reserve capacity, which puts a limit on how many batteries can earn at today’s rates.
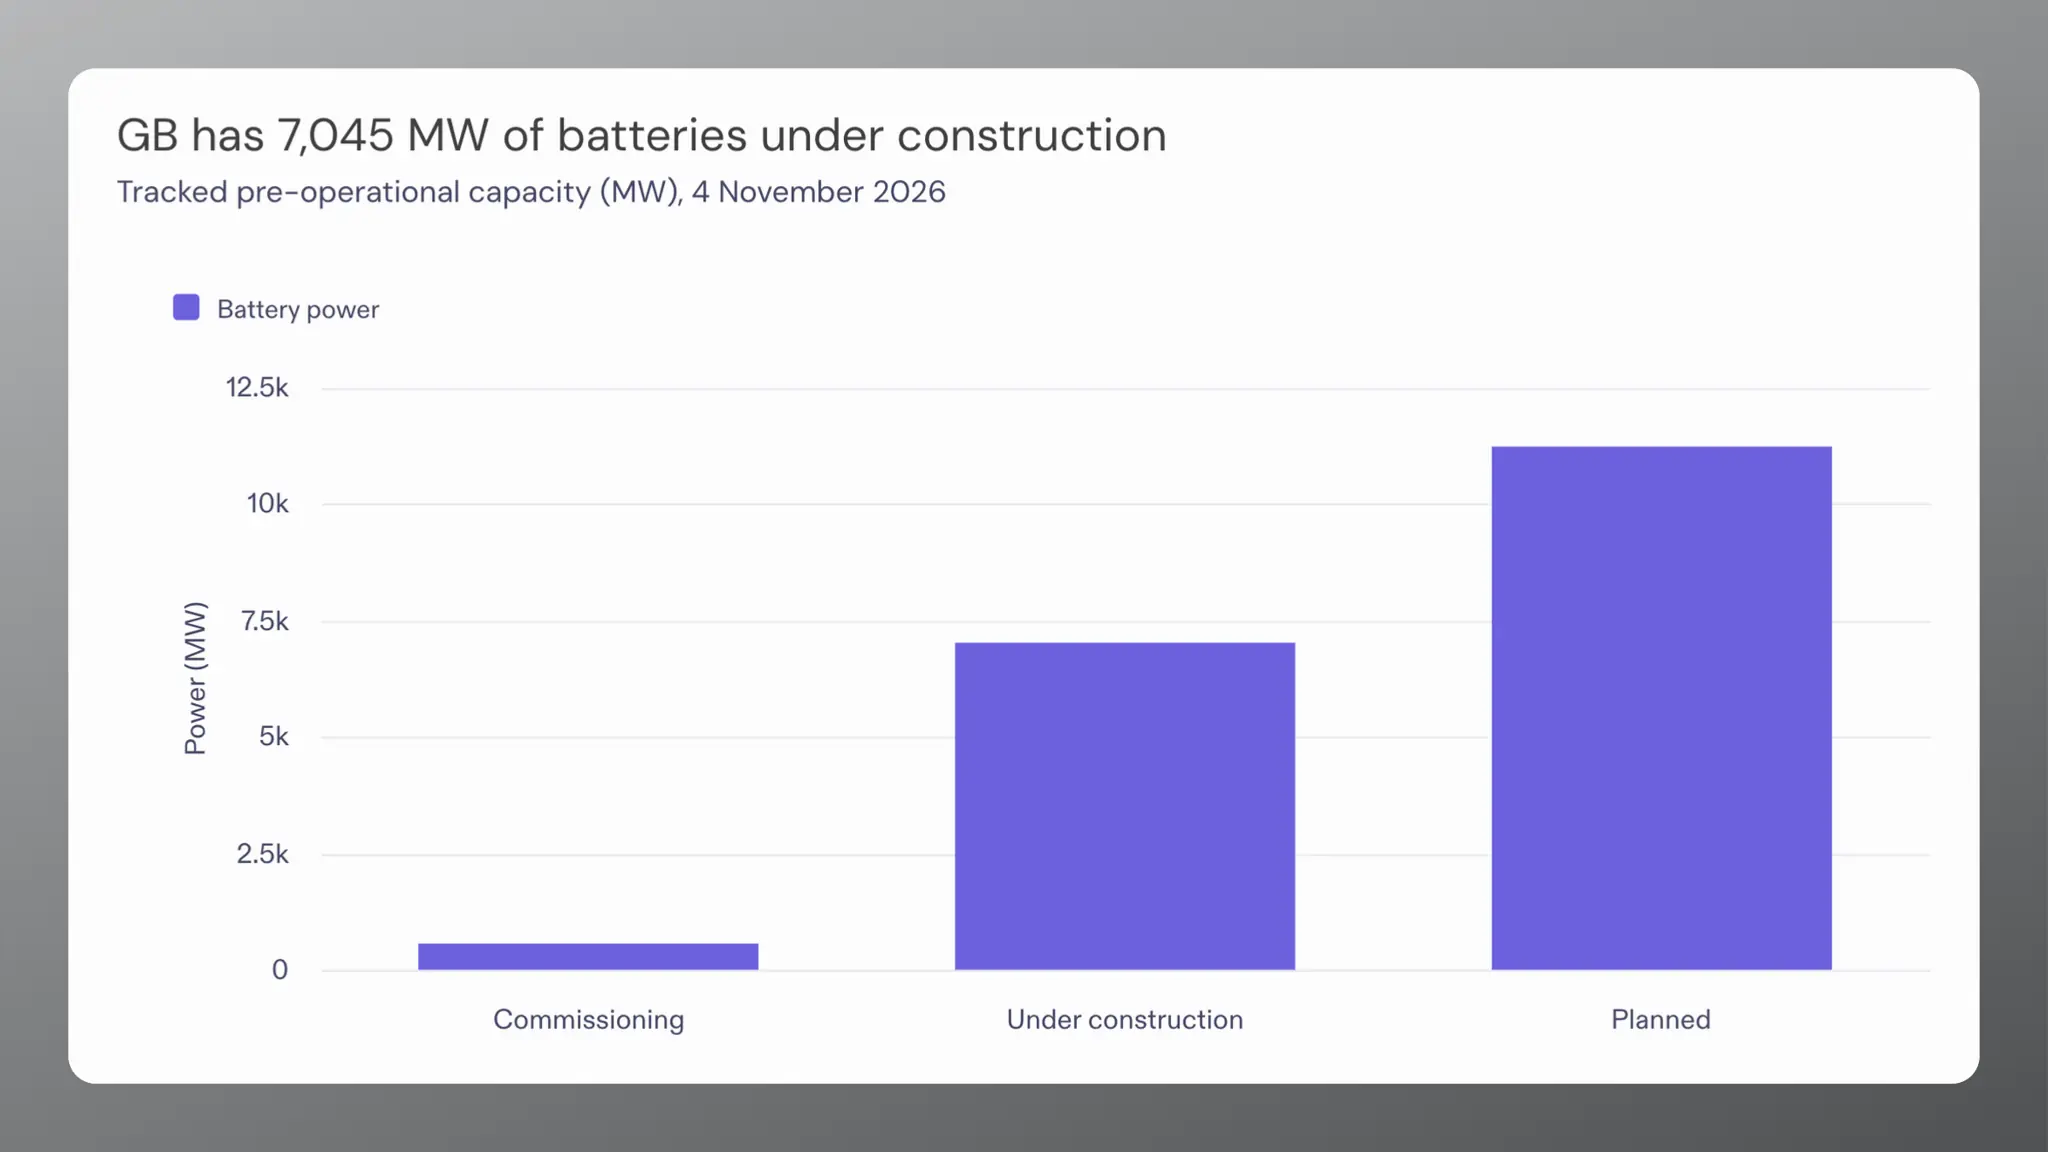
Developers added 455 MW of batteries in 2026. In our central case, installed capacity passes 1.8 GW in 2027. As more batteries compete for reserve contracts, annual revenue for a two-hour battery falls 63% to €165k/MW/yr by mid-2028.
In our November 2026 livestream, we looked at what wholesale trading can offer as reserve prices fall, how quickly new batteries can connect and which decisions in 2027 matter most for developers.
Key takeaways
- Polish power prices began tracking gas in April, even though coal still supplied much of Poland’s electricity. By 2028 we expect coal to cost more to run than gas. Coal plants then lose capacity market support after 2028.
- Grid reform is freeing up room for new projects, with applications to PSE down 80%. Financing the battery itself is a separate hurdle. For 2030 delivery, only 13.4 MW of a 100 MW four-hour battery qualifies for capacity payments.
- Balancing services accounted for 92% of Polish two-hour battery revenue in the year to September 2026. That leaves earnings particularly sensitive to competition for PSE’s reserve contracts.
- We expect installed battery capacity to exceed reserve demand in 2027. By 2030, Poland’s fleet reaches 4.4 times the reserve capacity PSE buys in our central case.
Polish wholesale prices have started tracking gas
As competition for reserves grows, more of a battery’s revenue will come from the wholesale arbitrage. In Poland, the fuel that sets the wholesale price is changing.
Coal and lignite still generate most of Poland’s electricity. From January to October 2026, Polish day-ahead prices rose 17%, a smaller increase than in Great Britain (31%) or Germany (26%). Over those months, though, Polish prices began to track a different fuel.
Until April, the day-ahead price closely followed the cost of running a coal plant. When gas prices rose after the outbreak of war in Iran, Polish power prices began to track gas instead. By October, it cost €186.5/MWh to generate electricity from gas, compared with €105.9/MWh from coal.
We expect those costs to cross by 2028. In our central case, gas prices fall through 2027 and 2028, while higher carbon prices under the EU Emissions Trading System weigh more heavily on coal. That makes coal the more expensive plant to run.
After 2028, EU rules also remove capacity market support for coal plants. The government aims to retire the last of them by 2036. Our central case assumes they close in 2040, by which time Poland has more than doubled its gas capacity.
An August heatwave pushed the evening price to PLN 1,870/MWh
On 4 August 2026, a heatwave prompted PSE to issue its second capacity market call of the year, requiring every contracted unit to deliver. Demand peaked at 21.2 GW, a level Poland regularly sees. What made the evening difficult was how little generation could replace solar as its output fell.
Around 5 GW of coal capacity was already offline for planned summer maintenance. Low river levels limited the cooling water available to other thermal plants, and wind farms generated only half their summer average.
Poland drew on pumped storage and imports from Germany and Lithuania to cover the shortfall. Some overseas plants with Polish capacity contracts, including units in Sweden, were needed on their own grids.
The day-ahead price reached PLN 1,870/MWh at 20:00, after the two-hour call had ended. For a battery operator, the value of storing an extra hour of energy depended on how long that evening peak lasted.
During the call itself, the imbalance price fell close to zero. This is the price at which deviations from scheduled generation and demand settle in real time. With contracted units already delivering at full output, PSE had little extra balancing to do during those two hours.
More solar has yet to bring more negative-price hours
The other side of a battery’s trading margin is the price it pays to charge. From 1 January to 26 October 2026, Poland recorded 303 hours of negative day-ahead prices, slightly fewer than in the same period in 2025. In Spain, the count rose from 547 to 693.
Sign up to read this article for free
Unlimited access to our free articles
Monthly access to 2 Global Research articles
Benchmarks, Forecasts, Ko and more