Swaps, Tolls, and Resource Adequacy: the state of BESS offtakes in CAISO
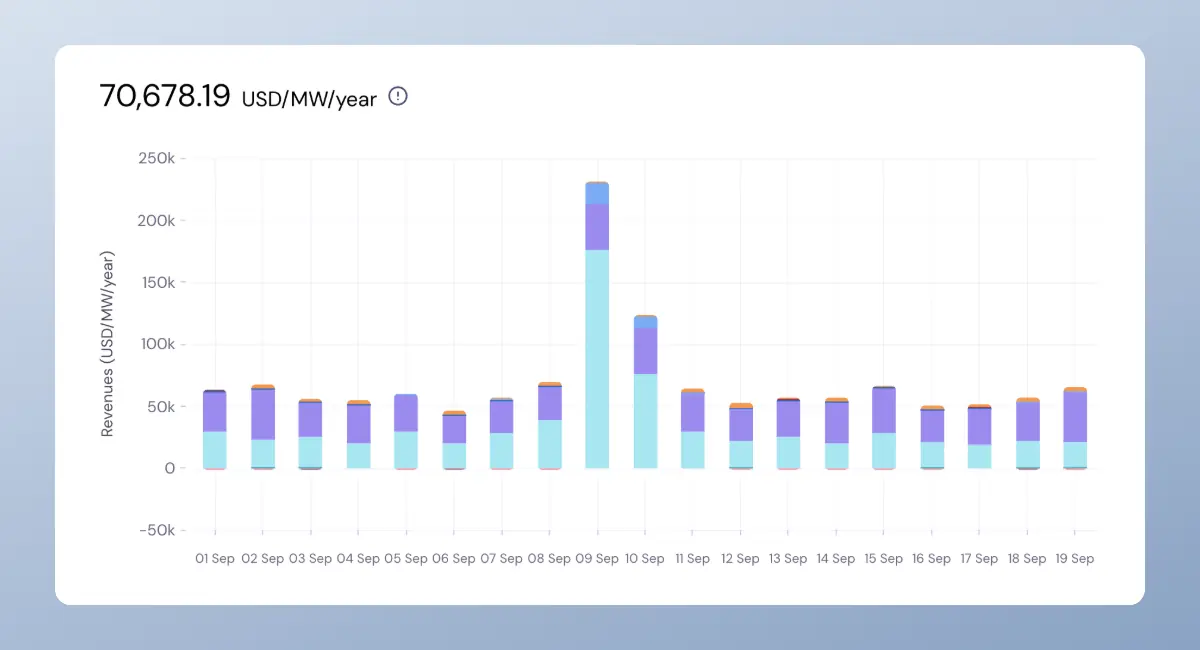
Capacity contracts are the foundation for battery revenues in California. These long-term agreements - which include both Resource Adequacy and offtakes - make up 80% of BESS revenues in CAISO today. They provide a floor to support the battery investment case as merchant revenues decline.
With wholesale battery revenues on track to settle at $40/kW for 2026 - the lowest year on record - developers today need to secure favorable terms on these capacity agreements to fill in the gap.
This analysis arms developers with insights on the state of the capacity market in California today - and a look at where we go from here.
The insights in this report are based on a proprietary dataset of publicly announced BESS agreements enriched with pricing data from company filings. The data covers 193 of the 292 BESS operating in CAISO as of September 2026.
What is happening with capacity prices in California?
In the first half of the 2020’s, Load Serving Entities (LSEs) contracted 11.5 GW of clean capacity to meet the CPUC’s Midterm Reliability procurement order. This procurement wave fueled early battery growth in the state.
Volume-weighted capacity prices across CAISO rose by 60% between 2020 and 2024, from $7.2/kW-month to $11.4/kW-month.
And in September 2024,
Sign up to read this article for free
Unlimited access to our free articles
Monthly access to 3 Global Research articles
Benchmarks, Forecasts, Ko and more